
We bring the entire architecture your family's wealth picture — portfolio, cash flow, tax coordination, estate, and legacy planning — under one coordinated roof so that complexity never stands between you and your intentions.
With decades of experience navigating various market cycles, we offer our perspective, discipline, and dedication to providing straightforward, hands on, customized wealth advisory solutions to assist in the proper stewardship of your assets. By taking a collaborative approach, we work with your tax and legal professionals to identify, simplify, and solve complex financial issues to help you achieve greater clarity, transparency, and control.
As an independent Registered Investment Advisor (RIA), our team has the freedom to provide objective, best-in-class solutions for you – without the financial incentives to recommend specific assets or proprietary products.
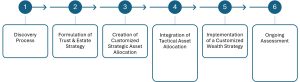
Investing the time to learn about you and your family, assets, liabilities, and risk exposures, enables us to design strategies and customize the relationship to your needs.
Working with your tax and legal advisors, we help analyze your income and estate tax circumstances to identify planning techniques that can be tailored to address your objectives.
Your customized asset allocation reflects risk, opportunities, and tax consideration across multiple entities while integrating your investment and estate plans.
Short-term adjustments seek to capitalize on temporary market distortions while deploying strategic tax strategies.
After comprehensive due diligence and analysis of expected results across multiple market scenarios, strategies are chosen from our expansive investment platforms.
In coordination with your tax and legal professionals, we conduct ongoing reviews and comprehensive reporting to ensure that your strategy adapts to changing financial and family needs.
We believe your wealth should serve your life, not complicate it. Significant wealth brings significant complexity — multiple advisors, private investments, capital calls, tax obligations, and generational decisions that rarely align on their own. We coordinate every moving piece: investment strategy, liquidity, tax management, trusts, and giving — so your capital reflects your intentions, supports the life you want now, and carries your values to the generations that follow.
Great planning begins with understanding — not products. We start by building a complete picture of your financial life: your balance sheet, cash flow, private investments, tax situation, estate documents, and the goals that sit behind them. From there, we design a strategic roadmap covering asset allocation, sustainable spending, liquidity, and wealth transfer. We then implement the plan and coordinate directly with your accountants, attorneys, bankers, and insurance advisors so nothing falls through the cracks.
Planning is not a one-time exercise. As markets move, capital needs arise, tax laws change, and your family’s priorities evolve, we revisit and refine the plan — monitoring the portfolio, forecasting cash needs, harvesting losses, and keeping every advisor working from the same set of facts. The result is a financial life that is organized, integrated, and always moving toward your goals.
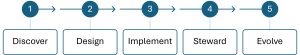
We begin by understanding your full financial picture — balance sheet, cash flow, private investments, entity and trust structures, tax posture, and existing advisor relationships — alongside the goals, obligations, and values that shape your decisions.
We build a strategic roadmap: asset allocation, sustainable spending, liquidity and capital call planning, tax-efficient investment structure, estate and wealth transfer strategy, and philanthropic intent — modeled together rather than in isolation.
We put the plan into motion. That includes portfolio construction and rebalancing, risk modeling, Donor Advised Fund and trust funding, and direct coordination with your accountants, attorneys, bankers, and insurance providers.
We monitor and refine continuously — forecasting cash needs, harvesting losses throughout the year, delivering consolidated reporting across public and private holdings, and keeping every advisor working from the same set of facts.
As markets shift, tax law changes, and your family’s priorities move forward, we revisit the plan. Wealth planning is not a document you complete — it’s a discipline you maintain.
Executives and business owners face a version of financial complexity that standard planning is not built for. Wealth is concentrated, often illiquid, and frequently tied to the same enterprise that generates income. Compensation arrives in forms that don’t behave like a paycheck — carried interest, equity grants, deferred comp, K-1 income, distributions with unpredictable timing. Tax exposure is lumpy and consequential. And the decisions that matter most tend to cluster around events: a raise, a vest, a liquidity event, a transition out of the business.
Concentration and liquidity. We map how much of your net worth sits in a single position or entity, model what a diversification path looks like, and build a liquidity plan that supports your spending without forcing sales at the wrong moment.
Cash flow that isn’t predictable. We forecast inflows and outflows annually — including capital calls, distributions, and variable compensation — so commitments are funded and reserves are sized before the call arrives, not after.
Carried interest and equity compensation. We plan around the tax and transfer implications of carry and equity, including gifting strategies to dynasty or legacy trusts, ILIT planning support, and timing decisions coordinated with your tax advisors.
Tax-aware investing. A year-round tax-loss harvesting overlay and access to tax-aware managers help offset carried interest distributions and K-1 taxable income rather than simply absorbing them.
Private investment administration. Subscription documents, capital call oversight, distribution tracking, reconciliation, K-1 collection, and consolidated reporting — the operational burden that grows quietly as your private book grows.
The transition itself. Whether the exit is years away or already in motion, we model the before-and-after: proceeds, tax, estate implications, and what the balance sheet needs to look like once the business is no longer the engine.
One coordinated team. Your CPA, attorney, banker, and insurance advisor all hold a piece of the picture. We sit at the center and keep them aligned, so decisions get made with the full context rather than in sequence.
Institutional capital carries obligations that personal capital does not. A foundation must fund a mission year after year while preserving purchasing power. The mission is to do so under a fiduciary standard, with a board that changes over time, and a spending requirement that doesn’t pause for difficult markets. We build a portfolio that reliably supports your mission for the long haul.
Spending policy and portfolio design. We help define what the organization can sustainably distribute, then build an asset allocation designed to support that spending while protecting long-term purchasing power. For private foundations, this includes planning around the annual distribution requirement, so it’s met deliberately rather than reactively.
Liquidity discipline. Grant cycles, program budgets, capital calls, and operating needs all draw on the same pool. We forecast those flows annually and structure liquidity tiers so commitments are funded on schedule without disrupting long-term positioning.
Investment policy support and design. We help draft, review, and maintain the Investment Policy Statement, the document that anchors decisions when markets are stressed and boards turn over. We use it as a benchmark to provide clarity to the board and hold us accountable for investment performance.
Private and alternative investments. An allocation to private and alternative markets is becoming the standard for foundations and endowments. We have exclusive access to institutional-caliber private and alternative investments. We handle the due diligence, subscription process, capital call and distribution administration, reconciliation, and manager communication. We pay close attention to how illiquidity interacts with the spending requirement.
Consolidated reporting for boards and committees. Performance across public and private holdings, presented against policy benchmarks and spending objectives, in a format built for board and investment committee review rather than for a portfolio manager.
Coordination across advisors. Auditors, accountants, counsel, and custodians each hold a piece of the picture. We sit at the center so filings, valuations, and reporting stay aligned and nothing gets rebuilt twice.
Continuity through board turnover. Committees rotate, treasurers change, and institutional memory erodes. Documented policy, consistent reporting, and a stable point of contact keep the strategy intact across transitions.

Managing Director,Financial Advisor

CFP®
Managing Director,Financial Advisor

CRPC™
Senior Wealth Strategy Associate, Associate Vice President
Client Relationship Manager

Director,Chair of Investment Committee
Harbor Investment Advisory, LLC is dually registered with the Securities and Exchange Commission ("SEC") as both a broker-dealer and an investment adviser and is a member of the Financial Industry Regulatory Authority ("FINRA") and the Securities Investor Protection Corporation ("SIPC"). These registrations and memberships in no way imply that the SEC has endorsed the entities, products or services discussed herein. All clients and investors should consult with their own tax, legal and accounting advisors before engaging in any potential strategy or investment. Investing involves risk, including risk of loss. Harbor Advisory is the marketing name of Harbor Investment Advisory, LLC.
©2010-2026 Harbor Investment Advisory, LLC. All rights reserved.